Quick Take
Recent changes to the tax code may affect how you choose to give to charitable organizations. Existing giving plans may need to be reviewed to make sure your giving is well timed and as tax efficient as possible.
If you itemize, the first 0.5% of your AGI that you give to charity no longer counts toward your deduction, and top-bracket taxpayers get less tax savings from every itemized deduction.
If you take the standard deduction, you can now deduct up to $1,000 of cash gifts ($2,000 for married couples filing jointly) given directly to charities.
The One Big Beautiful Bill Act, signed in July 2025, changed how charitable gifts are deducted, and 2026 is the first tax year the changes apply. If you itemize, part of each year’s giving will no longer produce a deduction. If you’re in the top tax bracket, every itemized deduction will also be worth a little less. If you take the standard deduction, you get a new charitable deduction of your own.
Most people won’t see any of this until they file their 2026 return next spring, when it’s too late to plan around it. A few changes to how and when you give, made before December 31, may win back much of what the new rules take away.
Two terms to know
Itemizing. Each year you either take the standard deduction or itemize, which means listing actual expenses like mortgage interest, state and local taxes and charitable gifts. Itemizing only pays off when those expenses add up to more than the standard deduction, which is why most households don’t do it.
Adjusted gross income (AGI). This is roughly your total income for the year, minus a few adjustments. You’ll find it on line 11a of your tax return.
Change 1: The first slice of your giving no longer counts
This applies only if you itemize. Starting in 2026, the first 0.5% of your AGI that you give to charity doesn’t count toward your deduction. It works a lot like the deductible on an insurance policy.
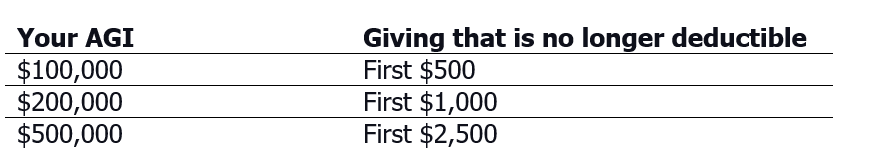
If you give less than that amount in a year, you get no charitable deduction at all. For most people, the portion that doesn’t count is simply lost. It doesn’t roll over to next year.
Higher earners who give modest amounts every year, a few hundred dollars here and there to local causes, will notice this most.
Change 2: A smaller tax break for top earners
This applies only to the top federal bracket, which in 2026 starts at taxable income of about $768,700 for married couples or $640,600 for single filers. If that isn’t you, skip ahead.
For these taxpayers, each dollar of itemized deductions, charitable gifts included, now saves about 35 cents in tax instead of 37 cents. A couple well into the top bracket with $100,000 of itemized deductions would pay roughly $2,000 more in tax.
Change 3: A new deduction if you don’t itemize
This one helps most families. Starting in 2026, if you take the standard deduction, you can also deduct up to $1,000 of charitable gifts ($2,000 for married couples filing jointly). The 0.5% floor from Change 1 doesn’t apply here.
A few rules to know:
· The gift must be cash. A check, credit card or bank transfer works. Gifts of appreciated stock don’t qualify.
· It must go directly to a charity. Money put into a donor-advised fund or a private foundation isn’t eligible.
· Anything over the limit doesn’t carry over to next year.
· The $1,000 and $2,000 limits don’t rise with inflation.
Group several years of gifts into one tax year
Say a married couple earns $300,000 and gives $10,000 to charity every year. If they itemize each year, the first $1,500 of their giving doesn’t count, every year. Over five years, that’s $7,500 of giving with no tax benefit.
Instead, they could put five years of giving, $50,000, into a donor-advised fund all at once. A donor-advised fund is an account held by a charitable organization. You get the deduction in the year you contribute, then recommend grants from the account to the charities you choose over the following years. The couple loses the first $1,500 once instead of five times. In the other years they take the standard deduction, and they can still deduct up to $2,000 of cash given directly to charities.
One caution: money in a donor-advised fund can’t come back to you. This approach works best when you’re confident about your giving plans for the next several years.
Give from your IRA if you’re 70½ or older
A qualified charitable distribution (QCD) sends money from your IRA directly to a charity, up to $111,000 per person in 2026. The money isn’t counted as income on your tax return, so none of the new limits apply to it.
It works whether you itemize or not. It also counts toward the required minimum distributions you’ll have to start taking in your 70s. And because it keeps your reported income lower, it can help with income-linked costs like Medicare premiums.
Two cautions: The money has to go straight from your IRA to the charity, not to you first and not to a donor-advised fund. And IRA providers need time to process these requests, so don’t wait until the last week of December.
Give appreciated investments instead of cash
If you own stocks or funds that have grown in value and you’ve held them for more than a year, consider giving the shares themselves. Neither you nor the charity pays capital gains tax on that growth, and the new law didn’t change that. To deduct the value of the gift, you’ll need to itemize.
Year-end checklist
Add up what you’ve given to charity so far this year.
Work out whether you’ll itemize or take the standard deduction for 2026. If you’re not sure, we can help you sort it out with your tax preparer.
If you’ll take the standard deduction, make sure your gifts are cash given directly to charities so they count toward the new $1,000 or $2,000 deduction.
If you’ll itemize, consider giving more this year, possibly through a donor-advised fund, to cover future years of giving.
If you’re 70½ or older, contact your IRA provider soon about sending gifts straight to charity.
If you’re giving stock, start early. It takes longer than writing a check.
Keep your receipts. Any single gift of $250 or more needs a written acknowledgment from the charity.
The bottom line
If you keep giving the way you always have, a little at a time each year, you may lose some of the tax benefit you used to get. A change in timing or method can win much of it back. The right approach depends on your income, your age and the accounts you own, so let’s talk it through before the year ends.
Contact us at 865-584-1850 or info@proffittgoodson.com